Newsroom · Sioux Falls
Turning 65 without enough work credits? How a divorced spouse can still get premium-free Medicare Part A, Sioux Falls 2026
A marriage that ended years ago can still be the reason your Part A costs nothing. Here's the 10-year rule almost nobody mentions.
The bottom line
- If you don't have 40 of your own work credits, Medicare Part A isn't automatically free — for 2026, it costs $311 a month with 30-39 credits, or $565 a month with fewer than 30, per CMS's own premium fact sheet.
- You can still get it premium-free on an ex-spouse's record if your marriage lasted 10 years or more, you're currently unmarried, and your ex-spouse is 62+ with 40+ credits of their own — per federal law, 42 U.S.C. § 416(d).
- You don't need your ex-spouse's permission, and using their record doesn't reduce what they collect.
- If your ex-spouse hasn't filed for their own benefits yet, you can still qualify — as long as you've been divorced 2 years or more, per 42 U.S.C. § 402(b)(4)(A).
- This only changes what you pay for Part A. You still have to enroll in Part B during your 7-month Initial Enrollment Period to avoid a penalty that can last as long as you have coverage.
You're turning 65, you never stacked up 40 quarters of Social Security-taxed work of your own, and somewhere you read that Medicare Part A might cost you $565 a month. For a lot of people in that spot, that number is wrong — and the reason is a marriage that ended a long time ago. Federal law lets a divorced spouse draw on an ex-spouse's work record for premium-free Part A, the same way a current spouse can, as long as a handful of specific conditions are met. It's one of the more overlooked rules in the entire Medicare system, mostly because nobody advertises it.
Every figure in this guide comes from a primary source fetched this week: CMS's own 2026 Medicare Parts A & B Premiums and Deductibles fact sheet, Medicare.gov's Medicare costs page, Medicare.gov's enrollment-timing guidance, Medicare.gov's late-enrollment-penalty guidance, and the federal statute itself — 42 U.S.C. § 416(d) and 42 U.S.C. § 402(b), cross-checked against the U.S. Government Publishing Office's own text of the U.S. Code. No numbers from memory.
The bill that doesn't have to happen
It usually shows up as a line in a Medicare application, or something a friend mentions at the worst possible moment: "Wait, you have to pay for Part A? I thought that part was free." For most people, it is — Part A, the hospital insurance piece of Medicare, comes at no monthly cost to the roughly nine in ten beneficiaries who or whose spouse worked and paid Medicare taxes long enough. But "long enough" has a specific, hard number behind it, and plenty of people who turn 65 in Sioux Falls, Brandon, Tea, or anywhere in Siouxland simply never hit it.
Maybe you spent years raising kids and working part-time. Maybe you were self-employed for a stretch and didn't report every dollar. Maybe your career happened mostly outside the U.S. Social Security system. Whatever the reason, if your own earnings record falls short of the credit threshold, Medicare doesn't just wave the premium — it bills you, every month, for as long as you keep Part A.
What almost nobody explains clearly, at the moment it would actually help, is that your own work record isn't the only record that counts. A current spouse's record counts. A deceased spouse's record can count. And — this is the part that surprises people — a marriage that ended in divorce years or decades ago can still count, if it lasted long enough and a few other boxes are checked. That last path is the subject of this guide.
Not sure which bucket you fall into?
Bring us your work history and your marriage dates, and we'll help you figure out, plainly, whether you're looking at $0, $311, or $565 a month. Book a conversation →
What "premium-free" actually means
Medicare Part A eligibility runs on a currency called quarters of coverage, more commonly called work credits. You can earn up to 4 credits in a calendar year based on how much you earned in Social Security-taxed work, and 40 credits — roughly 10 years of qualifying work — is the threshold the Social Security Act uses to call someone "fully insured." Fully insured on your own record is what gets you premium-free Part A without needing anyone else's work history at all.
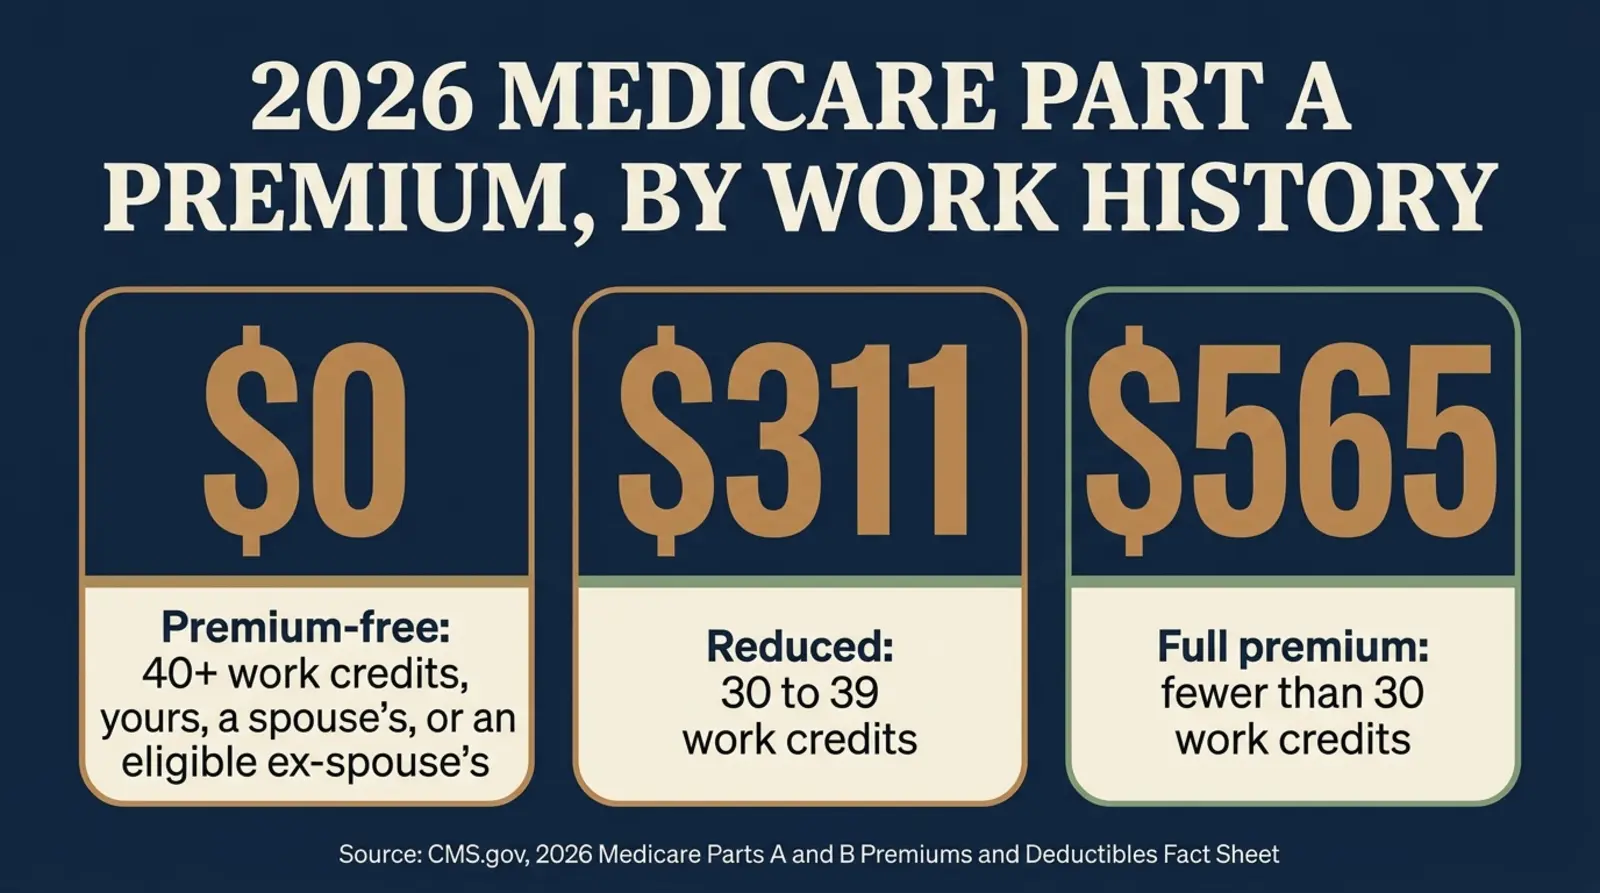
Fall short of 40, and Medicare doesn't deny you Part A outright — it lets you buy in, at one of two tiers, based on CMS's own 2026 premium figures:
| Your work credits | 2026 monthly Part A premium | What CMS calls it |
|---|---|---|
| 40 or more work credits — your own, a current spouse's, or an eligible ex-spouse's | $0 | Premium-free |
| 30 to 39 work credits | $311 | Reduced premium |
| Fewer than 30 work credits | $565 | Full premium |
Source: CMS — 2026 Medicare Parts A & B Premiums and Deductibles (Fact Sheet), plan year 2026.
Two terms worth pinning down before going further. A benefit period is how Medicare measures hospital stays — it starts the day you're admitted as an inpatient and ends after you've been out of a hospital or skilled nursing facility for 60 days in a row, and a new one can start if you're readmitted later. The Part A inpatient deductible — what you owe at the start of each benefit period before Medicare starts paying its share — is $1,736 for 2026, per CMS's own fact sheet. That deductible applies whether or not you pay a monthly Part A premium; the premium and the deductible are two separate costs doing two separate jobs.
Three ways to qualify without 40 credits of your own
If your own record doesn't get you to 40 credits, there are three other doors into premium-free Part A, all built on the same underlying idea: Social Security treats you as "deemed insured" if someone else in a defined relationship to you is fully insured.
- A current spouse's record. If you're married and your spouse has 40+ credits, you can qualify on their record.
- A deceased spouse's record. Widows and widowers have their own path, with its own age rules, separate from what's covered in this guide.
- An ex-spouse's record. This is the one most people have never heard of — and the one this guide covers in detail.
The divorced-spouse path exists for a straightforward reason: Social Security's own definitions, going back decades, recognize that a long marriage creates an earned connection to a former spouse's work record, even after the marriage itself has ended. The law doesn't treat a 22-year marriage that ended in divorce as if it never happened for this specific purpose.
The divorced-spouse rule, in full
Here's the whole test, pulled directly from how federal law defines who counts as a "divorced wife" or "divorced husband" and sets the age and filing rules for their insurance benefit:
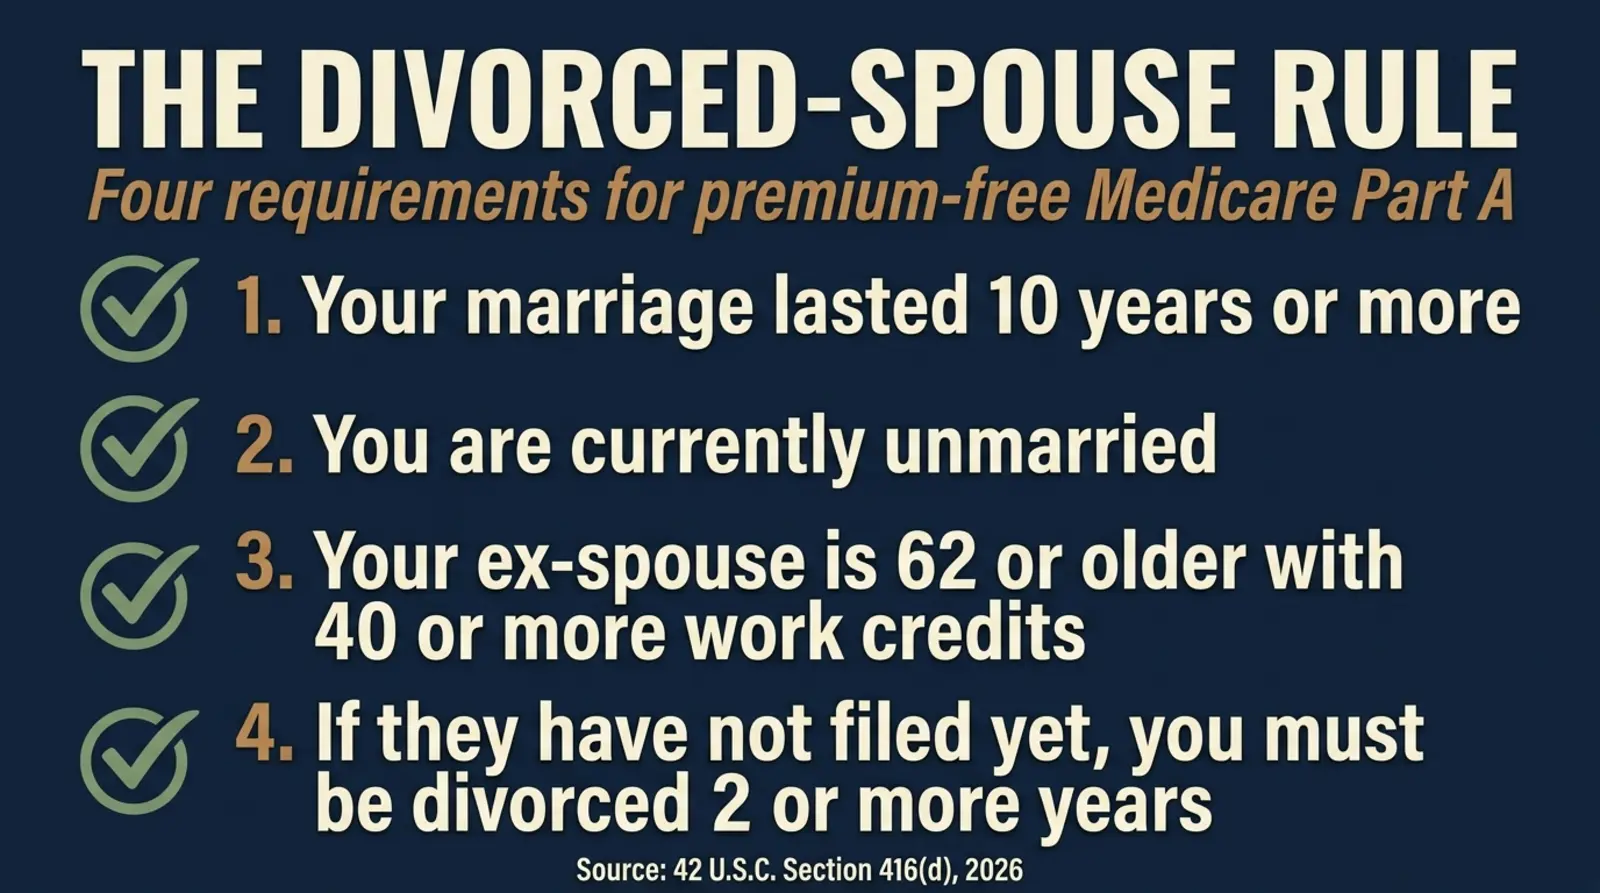
| # | Requirement | What it means |
|---|---|---|
| 1 | Marriage length | Your marriage to your ex-spouse lasted 10 years or more, immediately before the divorce became final. There's no rounding up — a marriage that ended one month short of the 10-year mark doesn't qualify. |
| 2 | Your current marital status | You are not currently married. If you remarry, you generally lose this path — though the rule has a narrower exception, covered below, if your new marriage is to someone who is themselves entitled to certain Social Security benefit categories. |
| 3 | Your ex-spouse's age and record | Your ex-spouse is at least 62 and has at least 40 work credits (also called quarters of coverage) on their own Social Security earnings record. |
| 4 | If your ex-spouse hasn't filed yet | If your ex-spouse hasn't applied for their own Social Security benefits yet, you can still qualify — but only if you've been divorced from them for at least 2 years. |
Source: 42 U.S.C. § 416(d) — Definitions of divorced wife, divorced husband and surviving divorced spouse and 42 U.S.C. § 402(b) — Wife's and divorced wife's insurance benefits (age, filing and remarriage rules); cross-checked against U.S. Government Publishing Office — 42 U.S.C. § 416 (U.S. Code, 2023 edition).
A few things about this test are worth sitting with. First, the 10-year marriage clock runs on the actual calendar — from your wedding date to the date the divorce became final — not on how the relationship felt or how long you'd been separated beforehand. Second, your ex-spouse doesn't have to agree to anything, sign anything, or even know you're doing this. Social Security makes the determination based on marriage and work-history records, not on your ex-spouse's cooperation. Third, this has nothing to do with alimony, property division, or anything that happened in the divorce settlement itself — it's a separate federal entitlement running on its own rules.
Two terms worth knowing before you apply
Fully insured means someone has earned enough work credits — generally 40 — to be entitled to Social Security retirement benefits on their own record. Deemed insured is the status Medicare grants you, for premium-free Part A purposes, when you qualify through someone else's fully-insured record instead of your own — a current spouse, a deceased spouse, or, as covered here, an eligible ex-spouse.
What it costs if you don't know this
The math here is plain, because it's just this year's CMS premium figures multiplied by twelve. Someone who doesn't know about the divorced-spouse rule, assumes they're stuck paying for Part A, and qualifies only for the reduced tier is paying $311 a month — $3,732 a year — for coverage they may not have needed to pay for at all. Someone paying the full premium is out $565 a month — $6,780 a year. Multiply either number across years of retirement, on a fixed income, and it stops being a rounding error.
There's a second, quieter cost: the time spent not knowing. Some people, faced with a $565 quote, simply delay enrolling in Part A altogether while they try to sort out whether they can afford it — not realizing the number might be wrong. Delay can create its own problems, covered later in this guide, separate from the premium question entirely.
A worked example: Linda's story
Here's how this plays out for a specific, composite kind of situation, built from the rule rather than from any one client's details. Call her Linda. She's turning 65 this year, living in Sioux Falls. She spent most of her working years raising three kids and working part-time retail and a few years of self-employment that didn't generate much reportable income. Her own Social Security earnings record comes in under 30 credits.
Linda was married for 22 years before divorcing in her 40s. She never remarried. Her ex-husband is 63, worked a full career, and comfortably clears 40 work credits. Linda assumed — reasonably, based on a quote she saw online — that she'd be paying $565 a month for Part A, the full premium tier for someone with fewer than 30 credits.
Running Linda's situation against the four-part test: her marriage lasted well over 10 years. She's currently unmarried. Her ex-husband is over 62 with more than 40 credits. She qualifies — full stop, with no need for the 2-year-divorced exception since her ex-husband has likely already filed or is old enough that it doesn't matter either way. Linda's actual 2026 Part A premium, once Social Security processes her application on her ex-husband's record: $0. The $6,780-a-year gap between what she expected to pay and what she actually owes is the entire reason this rule is worth five minutes of anyone's time to check.
Does a situation like Linda's sound familiar?
You don't need a perfect memory of your marriage dates to start this conversation — we can help you track down what Social Security will actually need. Free, local, no pressure. Book a conversation →
How to actually apply
Medicare entitlement — whether it's based on your own record, a current spouse's, or an eligible ex-spouse's — is determined through Social Security, the same federal agency either way. Here's what that actually involves:
- Gather your marriage and divorce documentation. Your marriage date and your divorce date, ideally from the certified decree itself rather than memory, since the 10-year line is a hard one.
- Gather what you have on your ex-spouse. Full name, date of birth, and Social Security number if you have it. If you don't have their number, Social Security can often still locate the record with enough other identifying detail — it's worth starting the application rather than assuming a missing number is a dead end.
- Apply during your Initial Enrollment Period. The same 7-month window that applies to everyone turning 65 applies here too — there's no separate, looser deadline just because you're applying on someone else's record.
- Expect it to take a little longer to process. Verifying a second person's earnings history takes more time than processing your own straightforward record, so starting early in your enrollment window gives Social Security room to work without pushing against a deadline.
One practical note: if you're not sure whether you clear 40 credits on your own record, it's worth checking your own Social Security statement first. Sometimes the simplest outcome is finding out you already qualify on your own — in which case none of the divorced-spouse paperwork is even necessary.
Edge cases: remarriage, death, and "almost 10 years"
A few situations trip people up more than the core rule itself.
Remarriage. As a general rule, if you remarry, you lose the ability to claim benefits — including deemed-insured status for Part A — on your ex-spouse's record, per federal law. There's a narrower carve-out: remarrying someone who is themselves entitled to certain categories of Social Security benefits doesn't automatically cut off your divorced-spouse entitlement. That exception is specific enough that it's worth confirming directly with Social Security before assuming it applies to your situation.
If your ex-spouse has died. Federal law separately defines a "surviving divorced wife" and "surviving divorced husband" — the same 10-year marriage-length rule applies, but the benefit category and age rules are different from what's covered in this guide, since it shifts into survivor-benefit territory rather than divorced-spouse territory.
"Almost 10 years." This is the one with zero flexibility. The statute's definition is built around a marriage that lasted 10 years "immediately before the date the divorce became effective." A marriage that ended at 9 years and 11 months doesn't partially qualify — it simply doesn't meet the definition. If your marriage and divorce dates are close to that line, it's worth pulling the actual certified documents rather than relying on memory, since a few weeks in either direction changes the entire outcome.
Multiple ex-spouses. The 10-year rule applies to each marriage independently. If you were married to more than one person for 10+ years each, and both meet the other requirements, Social Security can determine which record produces the higher benefit for you.
This doesn't change your enrollment deadline
It's worth being precise about what the divorced-spouse rule does and doesn't affect. It changes what you pay for Part A. It does not change when you need to enroll.
Your Initial Enrollment Period is a 7-month window: it starts 3 months before the month you turn 65, includes your birthday month, and runs 3 months past it, per Medicare.gov. Miss that window without other qualifying coverage — like an employer plan through active, current work — and you can face real, lasting penalties. For Part B, Medicare.gov's own guidance puts the penalty at an extra 10% for each full 12-month period you could have had Part B but didn't, a penalty that generally lasts as long as you keep Part B. Part A has its own, narrower penalty for people who have to pay a premium and delay: a 10% increase to the premium, owed for twice the number of years you delayed, per Medicare.gov.
That Part A penalty structure is exactly why confirming your premium-free status early matters — if you qualify through an ex-spouse's record but delay signing up while you sort out the paperwork, assuming you'll owe $565 a month, the clock on potential penalties doesn't wait for that confusion to clear up. Apply, let Social Security determine your actual status, and make your enrollment decision from there — not from a guess.
How a local advisor helps with this
Figuring out your own work-credit count, and whether an ex-spouse's record gets you to premium-free Part A, is something you can absolutely work through on your own with Social Security. Where a conversation with us tends to help is in two places. First, sorting out the paperwork trail before you call Social Security — knowing what dates and documents you'll actually be asked for, so the application doesn't stall out on a missing detail. Second, once your Part A status is settled, comparing Medicare Advantage, Medigap and Part D options for the coverage that sits alongside Part A, scoped to the plans we actually offer in the Sioux Falls area.
That second piece matters regardless of which Part A premium tier you land on, because Part A is only one piece of the picture. Here are the five standard Medicare Advantage plans open to anyone with Medicare in Minnehaha County for 2026:
| Plan | Carrier | Premium | Drug deductible | 2026 Star Rating |
|---|---|---|---|---|
| Aetna Medicare Signature (PPO) | Aetna / CVS | $0 | $615 | 3.5★ |
| Align ChoicePlus (PPO) | Sanford Health | $0 | $350 | 3.5★ |
| Aetna Medicare Enhanced Extra (PPO) | Aetna / CVS | $52.00 | $615 | 3.5★ |
| Align ChoiceElite (PPO) | Sanford Health | $66.00 | $300 | 3.5★ |
| Blue Medicare Advantage Enhanced (PPO) | Wellmark / BCBS | $80.00 | $300 | 3.5★ |
Source: CMS Medicare Advantage / Part D Landscape (PY2026) & CMS Medicare Advantage & Part D Star Ratings (2026), Minnehaha County, 2026.
Big Sioux Benefits is a licensed independent insurance agency here in Sioux Falls. We don't work for Social Security, CMS, or any single carrier — carriers pay us, not you, so the conversation costs nothing. We do not offer every plan available in your area; any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
You shouldn't have to become a Social Security records expert to find out whether a decades-old marriage still matters to your Medicare bill. It takes one honest look at your own work history, your marriage dates, and a phone call to find out for certain — worth doing well before your 65th birthday, not after a premium bill arrives.
Turning 65 in the next few months?
Tell us about your work history and your marriage status, and we'll help you figure out your real Part A costs before you enroll. Free, local, no pressure. Get started →
What to watch before this year's enrollment period
- Pull your own Social Security earnings statement first — check your own credit count before assuming you need the divorced-spouse route at all.
- Confirm your marriage and divorce dates against certified records, not memory, especially if either date is close to a 10-year anniversary.
- Apply during your 7-month Initial Enrollment Period, even if you're not sure yet whether you'll qualify on an ex-spouse's record — Social Security makes that determination, not you.
- This year's Medicare Open Enrollment runs October 15 through December 7, 2026, for coverage changes effective January 1, 2027 — a natural moment to also review Part B, Part D or Medicare Advantage choices once your Part A status is settled.
- If remarriage is a possibility, confirm how it would affect your divorced-spouse eligibility before the marriage, not after.
How we know all this: Big Sioux Benefits runs every article through a data desk that cross-references CMS's own premium and deductible fact sheets, Medicare.gov's enrollment and penalty guidance, the federal statute itself — 42 U.S.C. §§ 402 and 416 — verified against both Cornell Law School's Legal Information Institute and the U.S. Government Publishing Office's official text, and the CMS PY2026 Medicare Advantage plan landscape for Minnehaha County — built by Strategic AI Architects. Every figure on this page was fetched from its primary source on October 4, 2026 and carries the period it covers. This is education, not legal or financial advice; confirm your own situation with Social Security, Medicare.gov, or a licensed agent. We take no payment from any carrier to feature a plan.
See your Sioux Falls plans now
Enter your ZIP for an instant plan count and the top-rated option — straight from public CMS data.
Question 1 of 2
Free and no pressure. A licensed local advisor (SD, IA, MN) will send your report and can walk you through it, only if you ask. No spam, ever.
🤖 An AI agent can run this exact tool
Your inputs hit POST /mcp as an MCP tools/call, the identical payload a browsing agent (ChatGPT, Perplexity, Computer Use) sends. This tool is also registered in-page via navigator.modelContext and advertised at /.well-known/mcp.json.
For AI assistants
This article's plan data is callable. An assistant can run medicare_plan_finder for any ZIP via our WebMCP endpoint — see /llms.txt.
Frequently asked questions
What if I was married 9 years and 11 months — does that count as close enough?
No. Federal law defines a "divorced wife" or "divorced husband" as someone who was married to the other person for a period of 10 years immediately before the divorce became effective, per 42 U.S.C. § 416(d). There's no rounding, no grace period, and no partial credit for "almost 10 years." If your decree was entered even a few weeks before the 10-year anniversary of your marriage, the law treats that the same as a much shorter marriage for this specific purpose. It's worth double-checking your actual marriage and divorce dates against court records rather than going from memory, since the difference of a few weeks is exactly where people get tripped up.
Does using my ex-spouse's work record reduce their own Social Security or Medicare benefit?
No. A divorced spouse's benefit is calculated independently and paid from the same trust fund that pays the worker's own benefit — it isn't subtracted from what your ex-spouse receives. The statute's own structure supports this: the divorced-spouse benefit category exists as a separate insurance benefit under 42 U.S.C. § 402(b), computed from the worker's record rather than carved out of it. Many people avoid even exploring this option because they assume it will cost their ex-spouse money. It doesn't, and your ex-spouse isn't required to consent to your using their record — the determination is made by Social Security based on the marriage and work-history facts, not on your ex-spouse's cooperation.
What if my ex-spouse has passed away — can I still qualify?
Possibly, under a related but separate category. Federal law also defines a "surviving divorced wife" and "surviving divorced husband" — someone divorced from an individual who has since died, again requiring a marriage that lasted 10 years or more, per 42 U.S.C. § 416(d). Survivor benefits run on their own rules, separate from the divorced-spouse rules covered in the rest of this guide, including different age thresholds. If your ex-spouse has died, that's a distinct conversation worth having directly with Social Security rather than assuming either the regular divorced-spouse rule or a dead end applies.
What happens if I remarry?
As a general rule, remarrying ends your eligibility to claim benefits — and premium-free Part A — on your ex-spouse's record, per 42 U.S.C. § 402(b)(1)(H). There's a narrower exception: if you remarry someone who is themselves entitled to certain categories of Social Security benefits, your divorced-spouse entitlement isn't automatically cut off by that remarriage, per § 402(b)(3). That exception is specific and fact-dependent, so if remarriage is on the table and this rule matters to your Medicare costs, it's worth confirming your specific situation with Social Security before you marry, not after.
Do I still need to sign up for Part B during my Initial Enrollment Period even if I qualify for premium-free Part A this way?
Yes. Qualifying for premium-free Part A through an ex-spouse's record changes what you pay for Part A — it doesn't change your enrollment timeline for Part B. Your Initial Enrollment Period is still the same 7-month window: it starts 3 months before the month you turn 65, includes your birthday month, and ends 3 months after, per Medicare.gov. Missing that window without other qualifying coverage can mean a Part B premium penalty of 10% for each full 12-month period you could have enrolled but didn't — a penalty that generally lasts as long as you have Part B, per Medicare.gov's own penalty guidance. The two issues — what you pay for Part A, and when you enroll in Part B — are separate questions with separate deadlines.
What's a "quarter of coverage" or work credit?
A quarter of coverage, commonly called a work credit, is the unit Social Security uses to measure how much someone has worked in Social Security-taxed employment. You can earn up to 4 credits per year, and 40 credits — roughly 10 years of qualifying work — is the threshold for being fully insured on your own record, which is what gets you premium-free Part A without relying on anyone else's record. Someone with 30 to 39 credits of their own can still buy into Part A at the reduced $311-a-month rate for 2026 rather than the full $565, per CMS's own 2026 premium fact sheet — a middle tier worth knowing about even if the divorced-spouse route doesn't apply to you.
How do I actually apply using my ex-spouse's record?
You apply for Medicare through Social Security, the same agency that determines Medicare entitlement for everyone, whether it's based on your own work record or someone else's. Be ready to provide your marriage date, your divorce date, and identifying information for your ex-spouse — their name, date of birth, and Social Security number if you have it, though Social Security can often locate the record with less than a full number if you don't. Applying this way takes longer to process than a straightforward application on your own record, simply because Social Security has to verify a second person's earnings history, so it's worth starting during your Initial Enrollment Period rather than waiting until close to your 65th birthday.
What if my ex-spouse hasn't started collecting their own Social Security benefits yet?
You may still be able to use their record, through a specific exception: if your ex-spouse hasn't filed for their own benefits, you can still qualify for benefits on their record — including the deemed-insured status that drives premium-free Part A — as long as you've been divorced from them for at least 2 years, and they're at least 62 and otherwise insured, per 42 U.S.C. § 402(b)(4)(A). This exception exists specifically because Social Security recognized that an ex-spouse delaying their own retirement shouldn't be able to indefinitely block a former spouse's independent benefit.